Delray Beach · Serving Florida
Protection for now.
Income for what’s next.
Life insurance and annuities answer different questions. Start with the one that brought you here, then get plain-English guidance from a local insurance professional.
One life, changing needs
Your protection should move with you.
The right question is rarely “Which product is best?” It’s “What needs to be protected, for how long, and what flexibility do I need?”
Today
Protect the income your household relies on.
Along the way
Review coverage when work, family, or debt changes.
Retirement
Understand the gap between expenses and reliable income.
Legacy
Coordinate beneficiaries and the people you intend to protect.
Start with the decision
Tell us what you’re trying to solve.
No alphabet soup. No one-size-fits-all pitch. Choose a path and see the questions, tradeoffs, and next step that fit it.
Protect my family
Replace income, cover a mortgage, or make sure the people who depend on you have a plan.
Create retirement income
Understand how fixed and indexed annuities may fit alongside Social Security, pensions, and savings.
Review what I own
Get a plain-English second look at an existing policy or annuity before considering a change.
Protect a business
Explore key-person, buy-sell, and continuity needs with the right professional coordination.
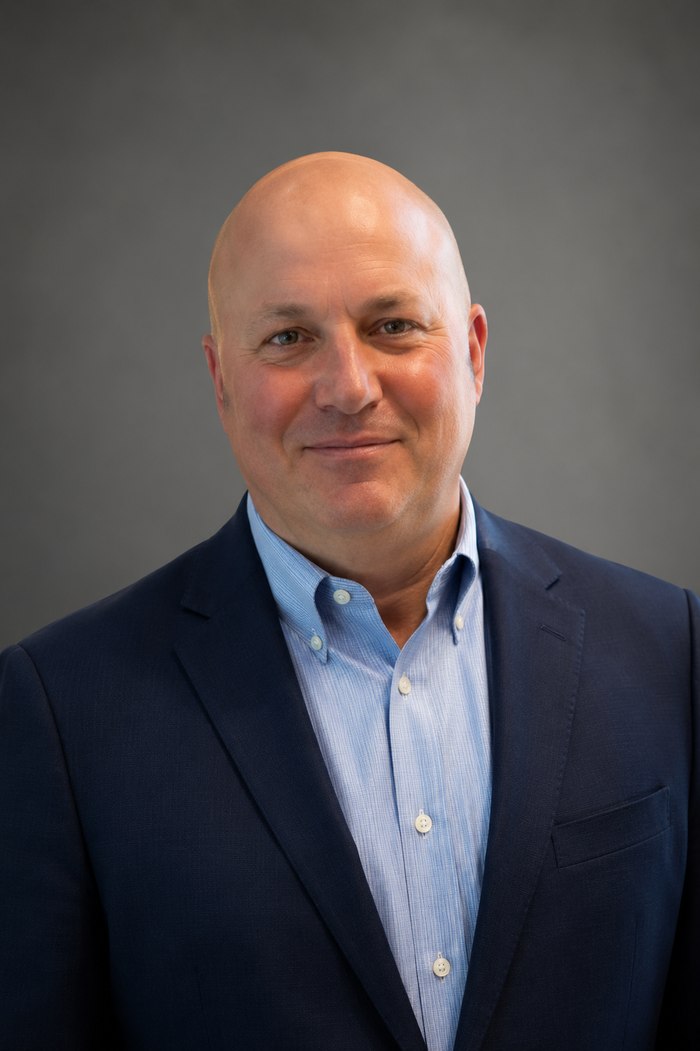
A local point of contact
Insurance guidance should feel human.
Intracoastal is designed around one accountable relationship: a clear conversation with Jason about the people, obligations, and timing behind the policy—not a handoff to a call center.
Listen first
Start with the need, not a product name.
Compare carefully
Review available options and material tradeoffs.
Stay available
Make room for questions before and after a decision.
The transparency standard
What you should understand before you decide.
Insurance products can be useful, but the contract details matter. Intracoastal’s content is built to make the consequential questions visible early.
How the agent is paid
Ask whether the professional receives a commission, from whom, and whether compensation differs by product.
What is guaranteed
Separate contractual guarantees from projections, assumptions, and indexed crediting illustrations.
How accessible the money is
Understand surrender periods, withdrawal limits, possible market value adjustments, and tax consequences.
When the product may not fit
Liquidity needs, time horizon, emergency reserves, existing coverage, and other income sources can change the answer.
South Florida roots · Florida reach
Local context. Statewide conversations.
Based in Delray Beach and serving clients across Florida by phone or video. In-person availability and exact service areas should be confirmed when you schedule.
Common questions
The useful kind of fine print.
What does “independent” mean?+
It means the conversation is not limited to one insurance company. The exact carriers and products available depend on licensing, appointments, state availability, underwriting, and your circumstances.
Can I get a life insurance estimate without a medical exam?+
You can begin with an online estimate. Final pricing and eligibility are determined by the insurer and may require health questions, records, or an exam.
Are annuities guaranteed?+
Some contract values or income benefits may be guaranteed, subject to the contract terms and the claims-paying ability of the issuing insurer. Other values may be indexed or variable. Access to funds, surrender charges, and tax consequences matter.
Will the first conversation result in a recommendation?+
Not necessarily. The purpose of an initial review is to understand the need, timing, existing coverage, and liquidity. Sometimes the right next step is to keep what you have or gather more information.
A clearer first step